


Form FWP TORONTO DOMINION BANK Filed by: TORONTO DOMINION BANK
FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/29/2026
- Wall Street ends lower as Alphabet revenue miss revives AI capex jitters
- Alphabet shares tumble 10% as earnings miss overshadows cloud boom
- Microsoft rises premarket as cloud strength drives earnings beat
- Caterpillar shares slump 10% despite earnings beat amid rapid AI buildout
- DoorDash to acquire Instacart in $17 billion deal
 Tweet
 Share
 E-mail
 |
Filed Pursuant to Rule 433
Registration Statement No. 333-283969
Dated October 29, 2026
|
|
Market Linked Securities – Auto-Callable with Contingent Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial Average®, the Russell 2000® Index and
the Shares of the State Street® Technology Select Sector SPDR® ETF due November 4, 2030
Term Sheet to Preliminary Pricing Supplement dated October 29, 2026
|
Summary of Terms
|
Issuer
|
The Toronto-Dominion Bank (the “Bank”)
|
||
|
Underwriters
|
TD Securities (USA) LLC and Wells Fargo Securities, LLC
|
||
|
Market Measures
|
The Dow Jones Industrial Average®, the Russell 2000® Index and the shares of the State Street® Technology Select Sector SPDR® ETF (each referred
to as a “Market Measure”)
|
||
|
Pricing Date*
|
October 30, 2026
|
||
|
Issue Date*
|
November 4, 2026
|
||
|
Face Amount and
Original Offering Price
|
$1,000 per security
|
||
|
Automatic Call
|
If the closing value of the lowest performing Market Measure on any call date (including the final calculation day) is greater than or equal to its starting value, the securities will be
automatically called, and on the related call settlement date you will be entitled to receive a cash payment per security equal to the face amount per Security plus the call premium applicable to the relevant call date.
|
||
|
Call Dates* and Call
Premiums
|
The call premium applicable to each call date will be a percentage of the face amount that increases for each call date based on a simple (non-compounding) return of at least approximately
14.40% per annum (to be determined on the pricing date). See “Call Dates and Call Premiums” on the following page.
|
||
|
Call Settlement Date
|
Three business days following the applicable call date (if the securities are called on the last call date, the call settlement date will be the stated maturity date)
|
||
|
Maturity Payment
Amount (per Security)
|
If the securities are not automatically called on any call date (including the final calculation day), the maturity payment amount per security, if any, will be based on
the performance of the lowest performing Market Measure on the final calculation day, calculated as follows:
• If the
ending value of the lowest performing Market Measure on the final calculation day is less than its starting value but greater than or equal to its
threshold value: $1,000.
• If the
ending value of the lowest performing Market Measure on the final calculation day is less than its threshold value:
$1,000 × performance factor of the lowest performing Market Measure on the final calculation day
|
||
|
Stated Maturity Date*
|
November 4, 2030
|
||
|
Starting Value
|
With respect to each Market Measure, its closing value on the pricing date
|
||
|
Ending Value
|
With respect to each Market Measure, its closing value on the final calculation day
|
||
|
Threshold Value:
|
With respect to each Market Measure, 75% of its starting value
|
||
|
Lowest Performing
Market Measure:
|
For any call date, the Market Measure with the lowest performance factor as of such call date.
|
||
|
Performance Factor:
|
With respect to a Market Measure on any call date, its closing value on such call date divided by its starting value (expressed as a percentage).
|
||
|
Calculation Agent
|
The Bank
|
||
|
Denominations
|
$1,000 and any integral multiple of $1,000
|
||
|
Agent Discount**
|
Up to 2.575%; dealers, including Wells Fargo Advisors, LLC (“WFA”), will receive a selling concession of up to 2.00%, and WFA may receive a distribution expense fee of 0.075%.
|
||
|
CUSIP / ISIN
|
89115NN83 / US89115NN832
|
||
|
Material Canadian and
U.S. Tax Consequences
|
See the preliminary pricing supplement.
|
|
*
|
Subject to change.
|
|
**
|
In respect of certain securities, we may pay a fee of up to $3.00 per security to selected securities dealers for marketing and other services in connection with the distribution of
the securities to other securities dealers.
|
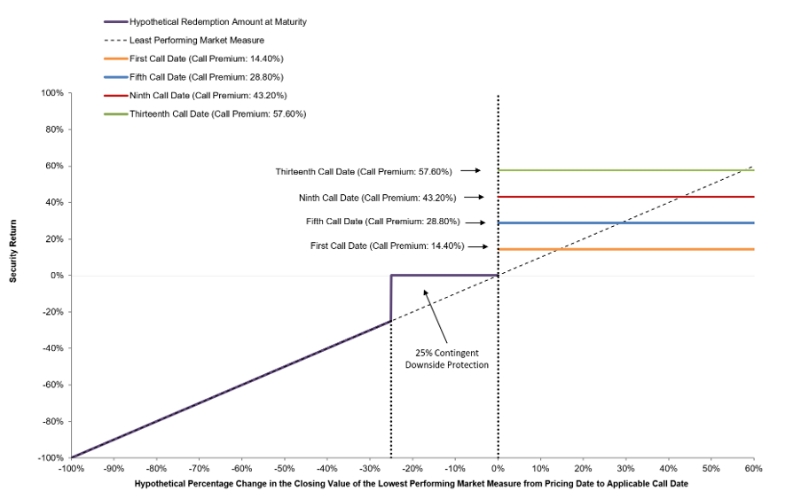
Hypothetical Payout Profile***
|
***
|
Assumes a call premium equal to the lowest possible call premium that may be determined on the pricing date.
|
If the securities are not automatically called and the ending value of the lowest performing Market Measure on the final calculation day is less than its
threshold value, you will have 1-to-1 downside exposure to the decrease in the value of the lowest performing Market Measure on the final calculation day and you will lose more than 25%, and possibly all, of the face amount of your securities at
stated maturity.
Any positive return on the securities will be limited to the applicable call premium, even if the closing value of the lowest performing Market Measure on the
applicable call date exceeds its starting value by significantly more than the percentage represented by such call premium. You will not participate in any increase of any Market Measure and the securities will not bear interest.
Our estimated value of the securities at the time the terms of your securities are set on the pricing date is expected to be between
$915.00 and $950.00 per security. The estimated value is expected to be less than the public offering price of the securities. See “Estimated Value of the Securities” in the preliminary pricing supplement.
Preliminary pricing supplement:
|
This introductory term sheet does not provide all of the information that an investor should consider prior to making
an investment decision. The securities have complex features and investing in the securities involves a number of risks. See “Selected Risk Considerations” beginning on page P-10 of the preliminary pricing supplement, “Risk
Factors” beginning on page PS-5 of the product supplement MLN-WF-1 dated February 26, 2025 (the “product supplement”) and “Risk Factors” on page 1 of the prospectus dated February 26, 2025 (the “prospectus”). The securities are not a bank
deposit and not insured or guaranteed by the Canada Deposit Insurance Corporation, the U.S. Federal Deposit Insurance Corporation or any other governmental agency or instrumentality of Canada or the United States.
|
Call Dates and Call Premiums
|
Call Date
|
Call Premium1
(as Percentage of
Face Amount)
|
Payment per Security
upon an Automatic
Call
|
Call Date
(cont.)
|
Call Premium1
(as Percentage of
Face Amount)
(cont.)
|
Payment per Security
upon an Automatic
Call
(cont.)
|
|
November 4, 2027
|
At least 14.40%
|
At least $1,144.00
|
August 6, 2029
|
At least 39.60%
|
At least $1,396.00
|
|
February 4, 2028
|
At least 18.00%
|
At least $1,180.00
|
November 5, 2029
|
At least 43.20%
|
At least $1,432.00
|
|
May 4, 2028
|
At least 21.60%
|
At least $1,216.00
|
February 4, 2030
|
At least 46.80%
|
At least $1,468.00
|
|
August 4, 2028
|
At least 25.20%
|
At least $1,252.00
|
May 6, 2030
|
At least 50.40%
|
At least $1,504.00
|
|
November 6, 2028
|
At least 28.80%
|
At least $1,288.00
|
August 5, 2030
|
At least 54.00%
|
At least $1,540.00
|
|
February 5, 2029
|
At least 32.40%
|
At least $1,324.00
|
October 30, 2030
(the “final calculation day”)
|
At least 57.60%
|
At least $1,576.00
|
|
May 4, 2029
|
At least 36.00%
|
At least $1,360.00
|
Selected Risk Considerations
The risks set forth below are discussed in detail in “Selected Risk Considerations” in the preliminary pricing supplement, “Risk Factors” in the product supplement and “Risk
Factors” in the prospectus. Please review those risk disclosures carefully.
|
•
|
If The Securities Are Not Automatically Called And The Ending Value Of The Lowest Performing Market Measure On The Final Calculation Day Is Less Than Its
Threshold Value, You Will Lose More Than 25%, And Possibly All, Of The Face Amount Of Your Securities At Stated Maturity.
|
|
•
|
No Periodic Interest Will Be Paid On The Securities.
|
|
•
|
The Potential Return On The Securities Is Limited To The Call Premium And You May Be Fully Exposed To The Decline In The Lowest Performing Market Measure
On The Final Calculation Day From Its Starting Value, But Will Not Participate In Any Positive Performance Of Any Market Measure.
|
|
•
|
The Securities Are Subject To The Full Risks Of Each Market Measure And Will Be Negatively Affected If Any Market Measure Performs Poorly, Even If Another Market Measure
Performs Favorably.
|
|
•
|
Your Return On The Securities Will Depend Solely On The Performance Of The Market Measure That Is The Lowest Performing Market Measure On Each Call Date,
And You Will Not Benefit In Any Way From The Performance Of A Better Performing Market Measure.
|
|
•
|
You Will Be Subject To Risks Resulting From The Relationship Among The Market Measures.
|
|
•
|
Higher Call Premiums Are Associated With Greater Risk.
|
|
•
|
You Will Be Subject To Reinvestment Risk.
|
|
•
|
A Call Settlement Date And The Stated Maturity Date May Be Postponed If A Call Date Is Postponed.
|
|
•
|
Investors Are Subject To The Bank’s Credit Risk, And The Bank’s Credit Ratings And Credit Spreads May Adversely Affect The Market Value Of The
Securities.
|
|
•
|
The Estimated Value Of Your Securities Is Expected To Be Less Than The Original Offering Price Of Your Securities.
|
|
•
|
The Estimated Value Of Your Securities Is Based On Our Internal Funding Rate.
|
|
•
|
The Estimated Value Of The Securities Is Based On Our Internal Pricing Models, Which May Prove To Be Inaccurate And May Be Different From The Pricing
Models Of Other Financial Institutions.
|
|
•
|
The Estimated Value Of Your Securities Is Not A Prediction Of The Prices At Which You May Sell Your Securities In The Secondary Market, If Any, And Such
Secondary Market Prices, If Any, Will Likely Be Less Than The Original Offering Price Of Your Securities And May Be Less Than The Estimated Value Of Your Securities.
|
|
•
|
The Temporary Price At Which We May Initially Buy The Securities In The Secondary Market May Not Be Indicative Of Future Prices Of Your Securities.
|
|
•
|
The Agent Discount, Offering Expenses And Certain Hedging Costs Are Likely To Adversely Affect Secondary Market Prices.
|
|
•
|
There May Not Be An Active Trading Market For The Securities — Sales In The Secondary Market May Result In Significant Losses.
|
|
•
|
If The Value Of Any Market Measure Changes, The Market Value Of Your Securities May Not Change In The Same Manner.
|
|
•
|
Any Payments On The Securities And Whether The Securities Are Automatically Called Will Depend Upon The Performance Of The Market Measures And Therefore
The Securities Are Subject To The Following Risks, Each As Discussed In More Detail In The Accompanying Product Supplement.
|
|
•
|
Investing In The Securities Is Not The Same As Investing In The Market Measures.
|
|
•
|
Historical Values Of A Market Measure Should Not Be Taken As An Indication Of The Future Performance Of Such Market Measure During The Term Of The
Securities.
|
|
•
|
Changes That Affect An Index May Adversely Affect The Value Of The Securities And Any Payments On The Securities.
|
|
•
|
We Cannot Control Actions By Any Of The Unaffiliated Companies Whose Securities Are Included In Any Index.
|
|
•
|
We And Our Affiliates And The Agents And Their Affiliates Have No Affiliation With Any Index Sponsor And Have Not Independently Verified Their Public
Disclosure Of Information.
|
|
•
|
Changes That Affect A Fund Or Its Fund Underlying Index May Adversely Affect The Value Of The Securities And Any Payments On The Securities.
|
|
•
|
We, The Agents And Our Or Their Respective Affiliates Cannot Control Actions By Any Of The Unaffiliated Companies Whose Securities Are Included In A Fund
Or Its Fund Underlying Index.
|
|
•
|
We, The Agents And Our Or Their Respective Affiliates Have No Affiliation With Any Fund Sponsor Or Fund Underlying Index Sponsor And Have Not Independently
Verified Their Public Disclosure Of Information.
|
|
•
|
An Investment Linked To The Shares Of A Fund Is Different From An Investment Linked To Its Fund Underlying Index.
|
|
•
|
There Are Management And Liquidity Risks Associated With A Fund.
|
|
•
|
Anti-dilution Adjustments Relating To The Shares Of A Fund Do Not Address Every Event That Could Affect Such Shares.
|
|
•
|
An Index Reflects Price Return, Not Total Return, And You Will Not Have Any Rights To The Constituents of an Index.
|
|
•
|
An Investment In The Securities Is Subject To Risks Associated With Investing In Stocks With Small Market Capitalizations
|
|
•
|
The Securities Are Subject To Risks Associated With The Sector Tracked By The State Street® Technology Select Sector SPDR® ETF
|
|
•
|
Trading And Business Activities By The Bank Or Its Affiliates May Adversely Affect The Market Value Of, And Any Amount Payable On, The Securities.
|
|
•
|
There Are Potential Conflicts Of Interest Between You And The Calculation Agent.
|
|
•
|
The Tax Consequences Of An Investment In The Securities Are Unclear.
|
|
|
The Bank has filed a registration statement (including a prospectus) with the SEC for the offering to which this communication relates. Before you invest, you should read the
prospectus in that registration statement and other documents the Bank has filed with the SEC for more complete information about the Bank and this offering. You may get these documents for free by visiting EDGAR on the SEC website at www.sec.gov.
Alternatively, the Bank, any Underwriter or any dealer participating in the offering will arrange to send you the prospectus if you request it by calling your financial advisor or by calling Wells Fargo Securities, LLC at 866-346-7732.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC, members SIPC, separate registered broker-dealers and
non-bank affiliates of Wells Fargo & Company.
2
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- TEXAS COMMUNITY BANCSHARES, INC. AND THE BANC OF SAN JACINTO COUNTY BANCSHARES, INC., THE PARENT OF THE BANK OF SAN JACINTO COUNTY, COLDSPRING, TEXAS, ANNOUNCE MERGER AGREEMENT
- KALDVIK AS (KLDVK): Update on refinancing process and extension of waiver period
- Laird Superfood to Report Third Quarter 2026 Financial Results on November 12, 2026
Create E-mail Alert Related Categories
SEC FilingsSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
