


Form 424B2 CITIGROUP INC
 Tweet
 Share
 E-mail
The information in this preliminary pricing supplement is not complete and may be changed. This preliminary pricing supplement, the accompanying product supplement, underlying supplement, prospectus supplement and prospectus are not an offer to sell these notes, nor are they soliciting an offer to buy these notes, in any state where the offer or sale is not permitted.
SUBJECT TO COMPLETION, DATED NOVEMBER 23, 2022
Filed Pursuant to Rule 424(b)(2)
Registration Statement Nos. 333-255302 and 333-255302-03
|
November----, 2022 Medium-Term Senior Notes, Series N Pricing Supplement No. 2022-USNCH15050 to Product Supplement
No. EA-09-01 |
 |
|
Citigroup Global Markets Holdings Inc. All Payments Due from Citigroup Global Markets Holdings Inc. Fully and Unconditionally Guaranteed by Citigroup Inc. |
|
Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 |
| n | Linked to the Energy Select Sector SPDR® Fund (the “underlying”) | |
| n | Unlike ordinary debt securities, the notes do not pay interest. Instead, the notes provide for a maturity payment amount that may be greater than or equal to the stated principal amount of the notes, depending on the performance of the underlying from the starting value to the ending value, subject to the maximum return. The maturity payment amount will reflect the following terms: | |
| n | If the ending value is greater than the starting value, you will receive the stated principal amount plus a positive return equal to 100% of the percentage increase in the value of the underlying from the starting value, subject to a maximum return of at least 32.00% (to be determined on the pricing date) of the stated principal amount | |
| n | If the ending value is less than or equal to the starting value, you will be repaid the stated principal amount but will not receive any positive return on your investment | |
| n | Repayment of principal at maturity regardless of underlying performance (subject to issuer credit risk) | |
| n | All payments on the notes are subject to the credit risk of Citigroup Global Markets Holdings Inc. and Citigroup Inc.; if Citigroup Global Markets Holdings Inc. and Citigroup Inc. default on their obligations, you could lose some or all of your investment | |
| n | No periodic interest payments or dividends | |
| n | The notes will not be listed on any securities exchange and, accordingly, may have limited or no liquidity. You should not invest in the notes unless you are willing to hold them to maturity. | |
The notes have complex features and investing in the notes involves risks not associated with an investment in conventional debt securities. See “Summary Risk Factors” beginning on page PS-6 and “Risk Factors” beginning on page PS-5 of the accompanying product supplement and beginning on page S-1 of the accompanying prospectus supplement.
Neither the Securities and Exchange Commission (the “SEC”) nor any state securities commission has approved or disapproved of the notes or determined that this pricing supplement or the accompanying product supplement, underlying supplement, prospectus supplement and prospectus are truthful or complete. Any representation to the contrary is a criminal offense.
The notes are unsecured debt obligations issued by Citigroup Global Markets Holdings Inc. and guaranteed by Citigroup Inc. All payments due on the notes are subject to the credit risk of Citigroup Global Markets Holdings Inc. and Citigroup Inc. None of Wells Fargo Securities, LLC (“Wells Fargo”) or any of its affiliates will have any liability to the purchasers of the notes in the event Citigroup Global Markets Holdings Inc. defaults on its obligations under the notes and Citigroup Inc. defaults on its guarantee obligations. The notes are not bank deposits and are not insured or guaranteed by the Federal Deposit Insurance Corporation or any other governmental agency, nor are they obligations of, or guaranteed by, a bank.
| Per Note | Total | |
| Public Offering Price(1) | $1,000.00 | $ |
| Maximum Underwriting Discount and Commission(2)(3) | $37.00 | $ |
| Proceeds to Citigroup Global Markets Holdings Inc.(2) | $963.00 | $ |
(1) Citigroup Global Markets Holdings Inc. currently expects that the estimated value of the notes on the pricing date will be at least $900.00 per note, which will be less than the public offering price. The estimated value of the notes is based on Citigroup Global Markets Inc.’s (“CGMI”) proprietary pricing models and our internal funding rate. It is not an indication of actual profit to CGMI or other of our affiliates, nor is it an indication of the price, if any, at which any person may be willing to buy the notes from you at any time after issuance. See “Valuation of the Notes” in this pricing supplement.
(2) CGMI, an affiliate of Citigroup Global Markets Holdings Inc., as the lead agent for the offering, expects to sell the notes to Wells Fargo, as agent. Wells Fargo will receive an underwriting discount and commission of up to 3.70% ($37.00) for each note it sells. Wells Fargo may pay selected dealers, which may include Wells Fargo Advisors (“WFA”) (the trade name of the retail brokerage business of its affiliates, Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC), a fixed selling commission of 2.00% ($20.00) for each note they sell. In addition to the selling commission allowed to WFA, Wells Fargo may pay $0.75 per note of the underwriting discount and commission to WFA as a distribution expense fee for each note sold by WFA. The total underwriting discount and commission and proceeds to Citigroup Global Markets Holdings Inc. shown above give effect to the actual underwriting discount and commission provided for the sale of the notes. See “Supplemental Plan of Distribution” below and “Use of Proceeds and Hedging” in the accompanying prospectus for further information regarding how we have hedged our obligations under the notes.
(3) In respect of certain notes sold in this offering, CGMI may pay a fee of up to $3.50 per note to selected securities dealers in consideration for marketing and other services in connection with the distribution of the notes to other securities dealers.
| Citigroup Global Markets Inc. | Wells Fargo Securities |
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 |  |
| Terms of the Notes |
| Underlying: | The Energy Select Sector SPDR® Fund |
| Issuer: | Citigroup Global Markets Holdings Inc., a wholly owned subsidiary of Citigroup Inc. |
| Guarantee: | All payments due on the notes are fully and unconditionally guaranteed by Citigroup Inc. |
| Stated Principal Amount: | $1,000 per note. References in this pricing supplement to a “note” are to a note with a stated principal amount of $1,000. |
| Pricing Date*: | November 30, 2022 |
| Issue Date*: | December 5, 2022 |
| Calculation Day*: | November 28, 2025, subject to postponement if such date is not a trading day or certain market disruption events occur as described in the accompanying product supplement. |
| Maturity Date*: | December 5, 2025, subject to postponement as described in the accompanying product supplement. |
| Maturity Payment Amount: |
For each $1,000 stated principal amount note you hold at maturity:
• If the ending value is greater than the starting value:
$1,000 plus the lesser of:
(i) $1,000 × underlying return × participation rate; and
(ii) the maximum return
• If the ending value is less than or equal to the starting value: $1,000
If the ending value is less than or equal to the starting value, you will be repaid the stated principal amount of the notes at maturity but will not receive any positive return on your investment. |
| Participation Rate: | 100% |
| Maximum Return: | At least 32.00% of the stated principal amount ($320 per note), to be determined on the pricing date. Because of the maximum return, the maturity payment amount will not exceed at least $1,320 per note. |
| Starting Value: | The closing value of the underlying on the pricing date |
| Ending Value: | The closing value of the underlying on the calculation day |
| Underlying Return: | (ending value – starting value) / starting value |
| Calculation Agent: | CGMI |
| Denominations: | $1,000 and any integral multiple of $1,000 |
| CUSIP / ISIN: | 17330YMN7 / US17330YMN75 |
* Expected. To the extent that the issuer makes any change to the expected pricing date or expected issue date, the calculation day and maturity date may also be changed in the issuer’s discretion to ensure that the term of the notes remains the same.
PS-2
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Additional Information |
The terms of the notes are set forth in the accompanying product supplement, prospectus supplement and prospectus, as supplemented by this pricing supplement. The accompanying product supplement, underlying supplement, prospectus supplement and prospectus contain important disclosures that are not repeated in this pricing supplement. For example, the accompanying product supplement contains important information about how the closing value of the underlying will be determined and other specified events with respect to the underlying. The accompanying underlying supplement contains information about the underlying that is not repeated in this pricing supplement. It is important that you read the accompanying product supplement, underlying supplement, prospectus supplement and prospectus together with this pricing supplement in deciding whether to invest in the notes. Certain terms used but not defined in this pricing supplement are defined in the accompanying product supplement.
When we refer to “we,” “us” and “our” in this pricing supplement, we refer only to Citigroup Global Markets Holdings Inc. and not to any of its affiliates, including Citigroup Inc.
You may access the product supplement, underlying supplement and prospectus supplement and prospectus on the SEC website www.sec.gov as follows (or if such address has changed, by reviewing our filings for the relevant date on the SEC website):
| · | Product Supplement No. EA-09-01 dated November 9, 2022: |
https://www.sec.gov/Archives/edgar/data/200245/000095010322019433/dp184001_424b2-wf0901.htm
| · | Underlying Supplement No. 10 dated May 11, 2021: https://www.sec.gov/Archives/edgar/data/200245/000095010321007028/dp150879_424b2-us10.htm |
| · | Prospectus Supplement and Prospectus, each dated May 11, 2021: https://www.sec.gov/Archives/edgar/data/200245/000119312521157552/d423193d424b2.htm |
PS-3
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Investor Considerations |
The notes are not appropriate for all investors. The notes may be an appropriate investment for investors who:
| · | seek exposure to any upside performance of the underlying without exposure to any decline in the underlying, by: |
| o | participating at the specified participation rate in the percentage increase, if any, from the starting value to the ending value, subject to the maximum return; and |
| o | providing for the repayment of the stated principal amount at maturity regardless of the performance of the underlying; |
| · | understand that if the ending value is less than or equal to the starting value, they will not receive any positive return on their investment in the notes; |
| · | are willing to forgo interest payments on the notes and dividends on the underlying; and |
| · | are willing to hold the notes to maturity. |
The notes may not be an appropriate investment for investors who:
| · | seek a liquid investment or are unable or unwilling to hold the notes to maturity; |
| · | seek certainty of receiving a positive return on their investment; |
| · | seek uncapped exposure to the upside performance of the underlying; |
| · | seek current income; |
| · | are unwilling to purchase notes with the estimated value set forth on the cover page; |
| · | are unwilling to accept the risk of exposure to the underlying; |
| · | seek exposure to the underlying but are unwilling to accept the risk/return trade-offs inherent in the maturity payment amount for the notes; |
| · | are unwilling to accept the credit risk of Citigroup Global Markets Holdings Inc. and Citigroup Inc.; or |
| · | prefer the lower risk of fixed income investments with comparable maturities issued by companies with comparable credit ratings. |
The considerations identified above are not exhaustive. Whether or not the notes are an appropriate investment for you will depend on your individual circumstances, and you should reach an investment decision only after you and your investment, legal, tax, accounting and other advisors have carefully considered the appropriateness of an investment in the notes in light of your particular circumstances. You should also review carefully the “Summary Risk Factors” herein and the “Risk Factors” in the accompanying product supplement for risks related to an investment in the notes. For more information about the underlying, please see the information provided below.
PS-4
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Determining Maturity Payment Amount |
On the maturity date, you will receive a cash payment per note (the maturity payment amount) calculated as follows:

PS-5
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Summary Risk Factors | ||
An investment in the notes is significantly riskier than an investment in conventional debt securities. The notes are subject to all of the risks associated with an investment in our conventional debt securities (guaranteed by Citigroup Inc.), including the risk that we and Citigroup Inc. may default on our obligations under the notes, and are also subject to risks associated with the underlying. Accordingly, the notes are appropriate only for investors who are capable of understanding the complexities and risks of the notes. You should consult your own financial, tax and legal advisors as to the risks of an investment in the notes and the appropriateness of the notes in light of your particular circumstances.
The following is a summary of certain key risk factors for investors in the notes. You should read this summary together with the more detailed description of risks relating to an investment in the notes contained in the section “Risk Factors” beginning on page PS-5 in the accompanying product supplement. You should also carefully read the risk factors included in the accompanying prospectus supplement and in the documents incorporated by reference in the accompanying prospectus, including Citigroup Inc.’s most recent Annual Report on Form 10-K and any subsequent Quarterly Reports on Form 10-Q, which describe risks relating to the business of Citigroup Inc. more generally.
You May Not Receive Any Positive Return On Your Investment In The Notes.
You will receive a positive return on your investment in the notes only if the ending value is greater than the starting value. If the ending value is equal to or less than the starting value, you will receive only the stated principal amount for each note you hold at maturity. As the notes do not pay any interest, even if the ending value is greater than the starting value, there is no assurance that your total return at maturity on the notes will be as great as could have been achieved on conventional debt securities of ours or of another issuer with a similar credit rating of comparable maturity.
The Notes Do Not Pay Interest.
Unlike conventional debt securities, the notes do not pay interest or any other amounts prior to maturity. You should not invest in the notes if you seek current income during the term of the notes.
Your Potential Return On The Notes Is Limited.
Your potential total return on the notes at maturity is limited to the maximum return. Your return on the notes will not exceed the maximum return, even if the underlying appreciates by significantly more than the maximum return. If the underlying appreciates by more than the maximum return, the notes will underperform an alternative investment providing 1-to-1 exposure to the performance of the underlying. When lost dividends are taken into account, the notes may underperform an alternative investment providing 1-to-1 exposure to the performance of the underlying and a pass-through of dividends even if the underlying appreciates by less than the maximum return.
You Will Not Receive Dividends Or Have Any Other Rights With Respect To The Underlying.
You will not receive any dividends with respect to the underlying. This lost dividend yield may be significant over the term of the notes. The payment scenarios described in this pricing supplement do not show any effect of lost dividend yield over the term of the notes. In addition, you will not have voting rights or any other rights with respect to the underlying.
Your Maturity Payment Amount Depends On The Value Of The Underlying On A Single Day.
Because your maturity payment amount depends on the value of the underlying solely on the calculation day, you are subject to the risk that the value of the underlying on that day may be lower, and possibly significantly lower, than on one or more other dates during the term of the notes. If you had invested directly in the underlying or in another instrument linked to the underlying that you could sell for full value at a time selected by you, or if the maturity payment amount were based on an average of values of the underlying, you might have achieved better returns.
Although The Notes Provide For The Repayment Of The Stated Principal Amount At Maturity, You May Nevertheless Suffer A Loss On Your Investment In Real Value Terms If The Percentage Change From The Starting Value to the Ending Value Is Less Than Or Not Sufficiently Greater Than Zero.
This is because inflation may cause the real value of the stated principal amount to be less at maturity than it is at the time you invest, and because an investment in the notes represents a forgone opportunity to invest in an alternative asset that does generate a positive real return. This potential loss in real value terms is significant given the term of the notes. You should carefully consider whether an
PS-6
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
investment that may not provide for any positive return on your investment, or may provide a return that is lower than the return on alternative investments, is appropriate for you.
The Notes Are Subject To The Credit Risk Of Citigroup Global Markets Holdings Inc. And Citigroup Inc.
If we default on our obligations under the notes and Citigroup Inc. defaults on its guarantee obligations, you may not receive anything owed to you under the notes.
The Notes Will Not Be Listed On Any Securities Exchange And You May Not Be Able To Sell Them Prior To Maturity.
The notes will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the notes. We have been advised that Wells Fargo currently intends to make a secondary market in relation to the notes. However, Wells Fargo may suspend or terminate making a market without notice, at any time and for any reason. If Wells Fargo suspends or terminates making a market, there may be no secondary market at all for the notes because it is likely that Wells Fargo will be the only broker-dealer that is willing to buy your notes prior to maturity. Accordingly, an investor must be prepared to hold the notes until maturity.
Sale Of The Notes Prior To Maturity May Result In A Loss Of Principal.
You will be entitled to receive at least the full stated principal amount of your notes, subject to the credit risk of Citigroup Global Markets Holdings Inc. and Citigroup Inc., only if you hold the notes to maturity. The value of the notes may fluctuate during the term of the notes, and if you are able to sell your notes prior to maturity, you may receive less than the full stated principal amount of your notes.
The Estimated Value Of The Notes On The Pricing Date, Based On CGMI’s Proprietary Pricing Models And Our Internal Funding Rate, Is Less Than The Public Offering Price.
The difference is attributable to certain costs associated with selling, structuring and hedging the notes that are included in the public offering price. These costs include (i) any selling concessions or other fees paid in connection with the offering of the notes, (ii) hedging and other costs incurred by us and our affiliates in connection with the offering of the notes and (iii) the expected profit (which may be more or less than actual profit) to CGMI or other of our affiliates and/or Wells Fargo or its affiliates in connection with hedging our obligations under the notes. These costs adversely affect the economic terms of the notes because, if they were lower, the economic terms of the notes would be more favorable to you. The economic terms of the notes are also likely to be adversely affected by the use of our internal funding rate, rather than our secondary market rate, to price the notes. See “The Estimated Value Of The Notes Would Be Lower If It Were Calculated Based On Wells Fargo’s Determination Of The Secondary Market Rate With Respect To Us” below.
The Estimated Value Of The Notes Was Determined For Us By Our Affiliate Using Proprietary Pricing Models.
CGMI derived the estimated value disclosed on the cover page of this pricing supplement from its proprietary pricing models. In doing so, it may have made discretionary judgments about the inputs to its models, such as the volatility of the underlying, the dividend yield on the underlying and interest rates. CGMI’s views on these inputs may differ from your or others’ views, and as an underwriter in this offering, CGMI’s interests may conflict with yours. Both the models and the inputs to the models may prove to be wrong and therefore not an accurate reflection of the value of the notes. Moreover, the estimated value of the notes set forth on the cover page of this pricing supplement may differ from the value that we or our affiliates may determine for the notes for other purposes, including for accounting purposes. You should not invest in the notes because of the estimated value of the notes. Instead, you should be willing to hold the notes to maturity irrespective of the initial estimated value.
The Estimated Value Of The Notes Would Be Lower If It Were Calculated Based On Wells Fargo’s Determination Of The Secondary Market Rate With Respect To Us.
The estimated value of the notes included in this pricing supplement is calculated based on our internal funding rate, which is the rate at which we are willing to borrow funds through the issuance of the notes. We expect that our internal funding rate is generally lower than Wells Fargo’s determination of the secondary market rate with respect to us, which is the rate that we expect Wells Fargo will use in determining the value of the notes for purposes of any purchases of the notes from you in the secondary market. If the estimated value included in this pricing supplement were based on Wells Fargo’s determination of the secondary market rate with respect to us, rather than our internal funding rate, it would likely be lower. We determine our internal funding rate based on factors such as the costs associated with the notes, which are generally higher than the costs associated with conventional debt securities, and our liquidity needs and preferences. Our internal funding rate is not an interest rate that is payable on the notes.
Because there is not an active market for traded instruments referencing our outstanding debt obligations, Wells Fargo may determine the secondary market rate with respect to us for purposes of any purchase of the notes from you in the secondary market based on the
PS-7
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
market price of traded instruments referencing the debt obligations of Citigroup Inc., our parent company and the guarantor of all payments due on the notes, but subject to adjustments that Wells Fargo may deem appropriate.
The Estimated Value Of The Notes Is Not An Indication Of The Price, If Any, At Which Any Person May Be Willing To Buy The Notes From You In The Secondary Market.
Any such secondary market price will fluctuate over the term of the notes based on the market and other factors described in the next risk factor. Moreover, unlike the estimated value included in this pricing supplement, we expect that any value of the notes determined for purposes of a secondary market transaction will be based on Wells Fargo’s determination of the secondary market rate with respect to us, which will likely result in a lower value for the notes than if our internal funding rate were used. In addition, we expect that any secondary market price for the notes will be reduced by a bid-ask spread, which may vary depending on the aggregate stated principal amount of the notes to be purchased in the secondary market transaction, and may be reduced by the expected cost of unwinding related hedging transactions. As a result, it is likely that any secondary market price for the notes will be less than the public offering price.
The Value Of The Notes Prior To Maturity Will Fluctuate Based On Many Unpredictable Factors.
The value of your notes prior to maturity will fluctuate based on the closing value of the underlying, the volatility of the closing value of the underlying, the dividend yield on the underlying, interest rates generally, the time remaining to maturity and our and Citigroup Inc.’s creditworthiness, as reflected in our secondary market rate, among other factors described under “Risk Factors—General Risk Factors Relating To All Notes— The Value Of Your Notes Prior To Maturity Will Fluctuate Based On Many Unpredictable Factors” in the accompanying product supplement. Changes in the value of the underlying may not result in a comparable change in the value of your notes. You should understand that the value of your notes at any time prior to maturity may be significantly less than the public offering price.
We Have Been Advised That, Immediately Following Issuance, Any Secondary Market Bid Price Provided By Wells Fargo, And The Value That Will Be Indicated On Any Brokerage Account Statements Prepared By Wells Fargo Or Its Affiliates, Will Reflect A Temporary Upward Adjustment.
The amount of this temporary upward adjustment will steadily decline to zero over the temporary adjustment period. See “Valuation of the Notes” in this pricing supplement.
The Energy Select Sector SPDR® Fund Is Subject To Concentrated Risks Associated With The Energy Sector.
The stocks included in the index underlying the Energy Select Sector SPDR® Fund and that are generally tracked by the Energy Select Sector SPDR® Fund are stocks of companies whose primary business is directly associated with the energy sector, including the following two sub-sectors: (i) oil, gas and consumable fuels and (ii) energy equipment and services. Because the notes are linked to the performance of the Energy Select Sector SPDR® Fund, an investment in the notes exposes investors to concentrated risks associated with investments in the energy sector.
Energy companies develop and produce crude oil and natural gas and/or provide drilling and other energy resources production and distribution related services. Stock prices for these types of companies are mainly affected by the business, financial and operating conditions of the particular company, as well as changes in prices for oil, gas and other types of fuels, which in turn largely depend on supply and demand for various energy products and services. Some of the factors that may influence supply and demand for energy products and services include: general economic conditions and growth rates; weather conditions; the cost of exploring for, producing and delivering oil and gas; technological advances affecting energy efficiency and energy consumption; the ability of the Organization of Petroleum Exporting Countries (OPEC) to set and maintain production levels of oil; currency fluctuations; inflation; natural disasters; civil unrest, acts of sabotage or terrorism; and other regional or global events. The profitability of energy companies may also be adversely affected by existing and future laws, regulations, government actions and other legal requirements relating to protection of the environment, health and safety matters and others that may increase the costs of conducting their business or may reduce or delay available business opportunities. Increased supply or weak demand for energy products and services, as well as various developments leading to higher costs of doing business or missed business opportunities, would adversely impact the performance of companies in the energy sector. The value of the notes may be subject to greater volatility and be more adversely affected by a single economic, political or regulatory occurrence affecting the energy sector or one of the sub-sectors of the energy sector than a different investment linked to securities of a more broadly diversified group of issuers.
PS-8
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
Our Offering Of The Notes Is Not A Recommendation Of The Underlying.
The fact that we are offering the notes does not mean that we or Wells Fargo or its affiliates believe that investing in an instrument linked to the underlying is likely to achieve favorable returns. In fact, as we and Wells Fargo and its affiliates are each part of respective global financial institutions, our affiliates and affiliates of Wells Fargo may have positions (including short positions) in the underlying or in instruments related to the underlying, and may publish research or express opinions, that in each case are inconsistent with an investment linked to the underlying. These and other activities of our affiliates or of Wells Fargo or its affiliates may affect the closing value of the underlying in a way that negatively affects the value of and your return on the notes.
The Closing Value Of The Underlying May Be Adversely Affected By Our Or Our Affiliates’, Or By Wells Fargo And Its Affiliates’, Hedging And Other Trading Activities.
We expect to hedge our obligations under the notes through CGMI or other of our affiliates and/or Wells Fargo or its affiliates, who may take positions in the underlying or in financial instruments related to the underlying and may adjust such positions during the term of the notes. Our affiliates and Wells Fargo and its affiliates may also take positions in the underlying or in financial instruments related to the underlying on a regular basis (taking long or short positions or both), for their accounts, for other accounts under their management or to facilitate transactions on behalf of customers. These activities could affect the closing value of the underlying in a way that negatively affects the value of and your return on the notes. They could also result in substantial returns for us or our affiliates or Wells Fargo and its affiliates while the value of the notes declines.
We And Our Affiliates And Wells Fargo And Its Affiliates May Have Economic Interests That Are Adverse To Yours As A Result Of Our And Their Respective Business Activities.
Our affiliates and Wells Fargo and its affiliates engage in business activities with a wide range of companies. These activities include extending loans, making and facilitating investments, underwriting securities offerings and providing advisory services. These activities could involve or affect the underlying in a way that negatively affects the value of and your return on the notes. They could also result in substantial returns for us or our affiliates or Wells Fargo or its affiliates while the value of the notes declines. In addition, in the course of this business, we or our affiliates or Wells Fargo or its affiliates may acquire non-public information, which will not be disclosed to you.
The Calculation Agent, Which Is An Affiliate Of Ours, Will Make Important Determinations With Respect To The Notes.
If certain events occur during the term of the notes, such as market disruption events and other events with respect to the underlying, CGMI, as calculation agent, will be required to make discretionary judgments that could significantly affect your return on the notes. In making these judgments, the calculation agent’s interests as an affiliate of ours could be adverse to your interests as a holder of the notes. See “Risk Factors—General Risk Factors Relating To All Notes—The Calculation Agent, Which Is An Affiliate Of Ours, Will Make Important Determinations With Respect To The Notes” in the accompanying product supplement.
The Notes Will Not Be Adjusted For All Events That Could Affect The Value Of The Shares Of The Underlying.
Certain events may occur during the term of the notes that have a dilutive effect on the value of the shares of the underlying or otherwise adversely affect the market price of such shares. The calculation agent will make certain adjustments for some of these events, as described under “General Terms of the Notes” in the accompanying product supplement. However, an adjustment will not be made for all events that could have a dilutive or adverse effect on such shares or their market price, such as ordinary dividends, partial tender offers or additional public offerings of shares, and the adjustments that are made may not fully offset the dilutive or adverse effect of the particular event. Accordingly, the occurrence of any event that has a dilutive or adverse effect on the shares of the underlying may adversely affect what you receive at maturity or, if applicable, any other payment owed to you under the notes. Unlike an investor in the notes, a direct holder of such shares may receive an offsetting benefit from any such event that may not be reflected in an adjustment to the terms of the notes; therefore, you may experience dilution or adverse consequences in a circumstance in which a direct holder would not.
If A Reorganization Event Occurs With Respect To The Underlying, The Calculation Agent May Make Adjustments To The Terms Of The Notes That Adversely Affect Your Return On The Notes.
If a reorganization event occurs with respect to the underlying, the calculation agent will have discretion to make such adjustments to the terms of the notes as the calculation agent determines appropriate to account for the economic effect on the notes of such event. In such an event, the calculation agent may, but is not required to, select a successor fund to which the notes may become linked
PS-9
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
thereafter. In any case, the adjustments made by the calculation agent to the terms of the notes may adversely affect the value of and your return on the notes.
The Value And Performance Of The Shares Of The Underlying May Not Completely Track The Performance Of The Underlying Index That The Underlying Seeks To Track Or The Net Asset Value Per Share Of The Underlying.
The underlying does not fully replicate the underlying index that it seeks to track and may hold securities different from those included in its underlying index. In addition, the performance of the underlying will reflect additional transaction costs and fees that are not included in the calculation of its underlying index. All of these factors may lead to a lack of correlation between the performance of the underlying and its underlying index. In addition, corporate actions with respect to the equity securities held by the underlying (such as mergers and spin-offs) may impact the variance between the performance of the underlying and its underlying index. Finally, because the shares of the underlying are traded on an exchange and are subject to market supply and investor demand, the closing value of the underlying may differ from the net asset value per share of the underlying.
During periods of market volatility, securities included in the underlying’s underlying index may be unavailable in the secondary market, market participants may be unable to calculate accurately the net asset value per share of the underlying and the liquidity of the underlying may be adversely affected. This kind of market volatility may also disrupt the ability of market participants to create and redeem shares of the underlying. Further, market volatility may adversely affect, sometimes materially, the price at which market participants are willing to buy and sell the shares of the underlying. As a result, under these circumstances, the closing value of the underlying may vary substantially from the net asset value per share of the underlying. For all of the foregoing reasons, the performance of the underlying may not correlate with the performance of its underlying index and/or its net asset value per share, which could materially and adversely affect the value of the notes and/or reduce your return on the notes.
Changes That Affect The Underlying May Affect The Value Of Your Notes.
The sponsor of the underlying may at any time make methodological changes or other changes in the manner in which it operates that could affect the value of the underlying. We are not affiliated with the underlying sponsor and, accordingly, we have no control over any changes the sponsor may make. Such changes could adversely affect the performance of the underlying and the value of and your return on the notes.
The Stated Maturity Date May Be Postponed If The Calculation Day Is Postponed.
The calculation day will be postponed for non-trading days and certain market disruption events. If such a postponement occurs, the maturity date will be postponed. For more information regarding adjustments to the calculation days and payment dates and the circumstances that may result in a market disruption event, see the relevant sections of the accompanying product supplement.
You Will Be Required To Recognize Taxable Income On The Notes Prior To Maturity.
If you are a U.S. holder of a note, you will be required to recognize taxable interest income in each year that you hold the note, even though you will not receive any payment in respect of the note prior to maturity (or earlier sale, exchange or retirement). In addition, any gain you recognize will be treated as ordinary interest income rather than capital gain. You should review the section of this pricing supplement entitled “United States Federal Tax Considerations.”
PS-10
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Hypothetical Examples and Returns |
The payout profile, return table and examples below illustrate how to determine the maturity payment amount on the notes, assuming the various hypothetical ending values indicated below. The examples are solely for illustrative purposes, do not show all possible outcomes and are not a prediction of what the actual maturity payment amount on the notes will be. The actual maturity payment amount will depend on the actual ending value.
The examples below are based on a hypothetical starting value of $100, rather than the actual starting value. For the actual starting value, see “Terms of the Notes” above. We have used this hypothetical value, rather than the actual value, to simplify the calculations and aid understanding of how the notes work. However, you should understand that the actual maturity payment amount on the notes will be calculated based on the actual starting value, and not the hypothetical value indicated below. The examples below assume that the maximum return will be set at the lowest value indicated in “Terms of the Notes” above. The actual maximum return will be determined on the pricing date.
Hypothetical Payout Profile

PS-11
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
Hypothetical Returns
|
Hypothetical ending value |
Hypothetical underlying return | Hypothetical maturity payment amount per note | Hypothetical total pre-tax rate of return |
| $200.00 | 100.00% | $1,320.00 | 32.00% |
| $175.00 | 75.00% | $1,320.00 | 32.00% |
| $150.00 | 50.00% | $1,320.00 | 32.00% |
| $140.00 | 40.00% | $1,320.00 | 32.00% |
| $132.00 | 32.00% | $1,320.00 | 32.00% |
| $130.00 | 30.00% | $1,300.00 | 30.00% |
| $120.00 | 20.00% | $1,200.00 | 20.00% |
| $110.00 | 10.00% | $1,100.00 | 10.00% |
| $100.00 | 0.00% | $1,000.00 | 0.00% |
| $90.00 | -10.00% | $1,000.00 | 0.00% |
| $80.00 | -20.00% | $1,000.00 | 0.00% |
| $70.00 | -30.00% | $1,000.00 | 0.00% |
| $60.00 | -40.00% | $1,000.00 | 0.00% |
| $50.00 | -50.00% | $1,000.00 | 0.00% |
| $25.00 | -75.00% | $1,000.00 | 0.00% |
| $0.00 | -100.00% | $1,000.00 | 0.00% |
Hypothetical Examples
Example 1—Upside Scenario A. The hypothetical ending value is $105 (a 5% increase from the starting value), which is greater than the starting value.
Maturity payment amount per note = $1,000 plus the lesser of:
(i) $1,000 × underlying return × participation rate and (ii) the maximum return
= $1,000 + the lesser of: (i) ($1,000 × 5% × 100%) and (ii) $320
= $1,000 + the lesser of: (i) $50 and (ii) $320
= $1,050
Because the underlying appreciated from the starting value to the hypothetical ending value, you would receive a total return at maturity equal to the upside performance of the underlying multiplied by the participation rate, which in this case is less than the maximum return.
Example 2—Upside Scenario B. The hypothetical ending value is $140 (a 40% increase from the starting value), which is greater than the starting value.
Maturity payment amount per note = $1,000 plus the lesser of:
(i) $1,000 × underlying return × participation rate and (ii) the maximum return
= $1,000 + the lesser of: (i) ($1,000 × 40% × 100%) and (ii) $320
= $1,000 + the lesser of: (i) $400 and (ii) $320
= $1,320
Because the underlying appreciated from the starting value to the hypothetical ending value and the upside performance of the underlying multiplied by the participation rate exceeds the maximum return, your total return at maturity would be limited to the maximum return in this case. In this scenario, an investment in the notes would underperform a hypothetical alternative investment providing 1-to-1 exposure to the appreciation of the underlying without a maximum return.
PS-12
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
Example 3—Par Scenario. The hypothetical ending value is $90 (a 10% decrease from the starting value), which is less than the starting value.
Maturity payment amount per note = $1,000
Because the hypothetical ending value is less than the starting value, you would be repaid the stated principal amount of your notes at maturity but would not receive any positive return on your investment.
PS-13
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| The Energy Select Sector SPDR® Fund |
The Energy Select Sector SPDR® Fund is an exchange-traded fund that seeks to provide investment results that, before expenses, correspond generally to the performance of publicly traded equity securities of companies in the Energy Select Sector Index. The Energy Select Sector Index is intended to provide an indication of the pattern of common stock price movements of companies that are components of the S&P 500® Index and are involved in the development or production of energy. The S&P Energy Select Sector Index includes companies in the following two industries: (i) oil, gas and consumable fuels and (ii) energy equipment and services.
The Energy Select Sector SPDR® Fund is managed by the Select Sector SPDR® Trust, a registered investment company. The Select Sector SPDR® Trust consists of numerous separate investment portfolios, including the Energy Select Sector SPDR® Fund. Information provided to or filed with the SEC by the Select Sector SPDR® Trust pursuant to the Securities Act of 1933, as amended, and the Investment Company Act of 1940, as amended, can be located by reference to SEC file numbers 333-57791 and 811-08837, respectively, through the SEC’s website at http://www.sec.gov. In addition, information may be obtained from other sources including, but not limited to, press releases, newspaper articles and other publicly disseminated documents. The underlying shares of the Energy Select Sector SPDR® Fund trade on the NYSE Arca under the ticker symbol “XLE.”
Please refer to the section “Fund Descriptions—The Select Sector SPDR® Funds” in the accompanying underlying supplement for additional information.
We have derived all information regarding the Energy Select Sector SPDR® Fund from publicly available information and have not independently verified any information regarding the Energy Select Sector SPDR® Fund. This pricing supplement relates only to the notes and not to the Energy Select Sector SPDR® Fund. We make no representation as to the performance of the Energy Select Sector SPDR® Fund over the term of the notes.
The notes represent obligations of Citigroup Global Markets Holdings Inc. (guaranteed by Citigroup Inc.) only. The sponsor of the Energy Select Sector SPDR® Fund is not involved in any way in this offering and has no obligation relating to the notes or to holders of the notes.
Historical Information
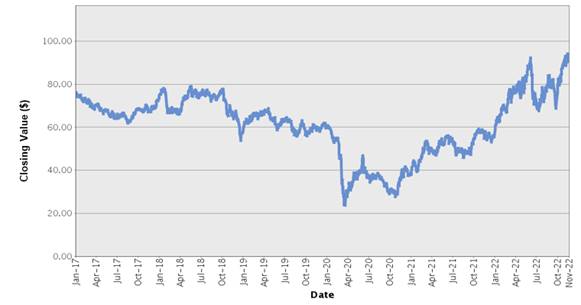
The closing value of the Energy Select Sector SPDR® Fund on November 22, 2022 was $93.22.
The graph below shows the closing value of the Energy Select Sector SPDR® Fund for each day such value was available from January 3, 2017 to November 22, 2022. We obtained the closing values from Bloomberg L.P., without independent verification. You should not take historical closing values as an indication of future performance.
PS-14
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| United States Federal Tax Considerations |
In the opinion of our counsel, Davis Polk & Wardwell LLP, which is based on current market conditions, the notes should be treated as “contingent payment debt instruments” for U.S. federal income tax purposes, as described in the section of the accompanying product supplement called “United States Federal Tax Considerations—Tax Consequences to U.S. Holders—Notes Treated as Contingent Payment Debt Instruments,” and the remaining discussion is based on this treatment.
If you are a U.S. Holder (as defined in the accompanying product supplement), you will be required to recognize interest income during the term of the notes at the “comparable yield,” which generally is the yield at which we could issue a fixed-rate debt instrument with terms similar to those of the notes, including the level of subordination, term, timing of payments and general market conditions, but excluding any adjustments for the riskiness of the contingencies or the liquidity of the notes. We are required to construct a “projected payment schedule” in respect of the notes representing a payment the amount and timing of which would produce a yield to maturity on the notes equal to the comparable yield. Assuming you hold the notes until their maturity, the amount of interest you include in income based on the comparable yield in the taxable year in which the notes mature will be adjusted upward or downward to reflect the difference, if any, between the actual and projected payment on the notes at maturity as determined under the projected payment schedule. However, special rules may apply if the payment at maturity on the notes is treated as becoming fixed prior to maturity. See “United States Federal Tax Considerations—Tax Consequences to U.S. Holders—Notes Treated as Contingent Payment Debt Instruments” in the accompanying product supplement for a more detailed discussion of the special rules.
Upon the sale, exchange or retirement of the notes prior to maturity, you generally will recognize gain or loss equal to the difference between the proceeds received and your adjusted tax basis in the notes. Your adjusted tax basis will equal your purchase price for the notes, increased by interest previously included in income on the notes. Any gain generally will be treated as ordinary income, and any loss generally will be treated as ordinary loss to the extent of prior interest inclusions on the note and as capital loss thereafter.
We have determined that the comparable yield for a note is a rate of %, compounded semi-annually, and that the projected payment schedule with respect to a note consists of a single payment of $ at maturity.
Neither the comparable yield nor the projected payment schedule constitutes a representation by us regarding the actual amount that we will pay on the notes.
Non-U.S. Holders. Subject to the discussions below regarding Section 871(m) and in “United States Federal Tax Considerations—Tax Consequences to Non-U.S. Holders” and “—FATCA” in the accompanying product supplement, if you are a Non-U.S. Holder (as defined in the accompanying product supplement) of the notes, under current law you generally will not be subject to U.S. federal withholding or income tax in respect of any payment on or any amount received on the sale, exchange or retirement of the notes, provided that (i) income in respect of the notes is not effectively connected with your conduct of a trade or business in the United States, and (ii) you comply with the applicable certification requirements. See “United States Federal Tax Considerations—Tax Consequences to Non-U.S. Holders” in the accompanying product supplement for a more detailed discussion of the rules applicable to Non-U.S. Holders of the notes.
As discussed under “United States Federal Tax Considerations—Tax Consequences to Non-U.S. Holders—Dividend Equivalents Under Section 871(m) of the Code” in the accompanying product supplement, Section 871(m) of the Internal Revenue Code of 1986, as amended and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% withholding tax on dividend equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities (“Underlying Securities”) or indices that include Underlying Securities. Section 871(m) generally applies to instruments that substantially replicate the economic performance of one or more Underlying Securities, as determined based on tests set forth in the applicable Treasury regulations. However, the regulations, as modified by an Internal Revenue Service (“IRS”) notice, exempt financial instruments issued prior to January 1, 2025 that do not have a “delta” of one. Based on the terms of the notes and representations provided by us as of the date of this preliminary pricing supplement, our counsel is of the opinion that the notes should not be treated as transactions that have a “delta” of one within the meaning of the regulations with respect to any Underlying Security and, therefore, should not be subject to withholding tax under Section 871(m). However, the final determination regarding the treatment of the notes under Section 871(m) will be made as of the pricing date for the notes, and it is possible that the notes will be subject to withholding under Section 871(m) based on the circumstances as of that date.
A determination that the notes are not subject to Section 871(m) is not binding on the IRS, and the IRS may disagree with this treatment. Moreover, Section 871(m) is complex and its application may depend on your particular circumstances, including your other transactions. You should consult your tax adviser regarding the potential application of Section 871(m) to the notes.
If withholding tax applies to the notes, we will not be required to pay any additional amounts with respect to amounts withheld.
PS-15
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
You should read the section entitled “United States Federal Tax Considerations” in the accompanying product supplement. The preceding discussion, when read in combination with that section, constitutes the full opinion of Davis Polk & Wardwell LLP regarding the material U.S. federal tax consequences of owning and disposing of the notes.
You should also consult your tax adviser regarding all aspects of the U.S. federal tax consequences of an investment in the notes and any tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
PS-16
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Supplemental Plan of Distribution |
Pursuant to the terms of the Amended and Restated Global Selling Agency Agreement, dated April 7, 2017, CGMI, acting as principal, will purchase the notes from Citigroup Global Markets Holdings Inc. CGMI, as the lead agent for the offering, expects to sell the notes to Wells Fargo, as agent. Wells Fargo will receive an underwriting discount and commission of up to 3.70% ($37.00) for each note it sells. Wells Fargo may pay selected dealers, which may include WFA, a fixed selling commission of 2.00% ($20.00) for each note they sell. In addition to the selling commission allowed to WFA, Wells Fargo may pay $0.75 per note of the underwriting discount and commission to WFA as a distribution expense fee for each note sold by WFA.
In addition, in respect of certain notes sold in this offering, CGMI may pay a fee of up to $3.50 per note to selected securities dealers in consideration for marketing and other services in connection with the distribution of the notes to other securities dealers.
| Valuation of the Notes |
CGMI calculated the estimated value of the notes set forth on the cover page of this pricing supplement based on proprietary pricing models. CGMI’s proprietary pricing models generated an estimated value for the notes by estimating the value of a hypothetical package of financial instruments that would replicate the payout on the notes, which consists of a fixed-income bond (the “bond component”) and one or more derivative instruments underlying the economic terms of the notes (the “derivative component”). CGMI calculated the estimated value of the bond component using a discount rate based on our internal funding rate. CGMI calculated the estimated value of the derivative component based on a proprietary derivative-pricing model, which generated a theoretical price for the instruments that constitute the derivative component based on various inputs, including the factors described under “Summary Risk Factors—The Value Of The Notes Prior To Maturity Will Fluctuate Based On Many Unpredictable Factors” in this pricing supplement, but not including our or Citigroup Inc.’s creditworthiness. These inputs may be market-observable or may be based on assumptions made by CGMI in its discretionary judgment.
The estimated value of the notes is a function of the terms of the notes and the inputs to CGMI’s proprietary pricing models. As of the date of this preliminary pricing supplement, it is uncertain what the estimated value of the notes will be on the pricing date because certain terms of the notes have not yet been fixed and because it is uncertain what the values of the inputs to CGMI’s proprietary pricing models will be on the pricing date.
We have been advised that, for a period of approximately three months following issuance of the notes, the price, if any, at which Wells Fargo would be willing to buy the notes from investors, and the value that will be indicated for the notes on any brokerage account statements prepared by Wells Fargo or its affiliates, will reflect a temporary upward adjustment from the price or value that would otherwise be determined. This temporary upward adjustment represents a portion of the costs associated with selling, structuring and hedging the notes that are included in the public offering price of the notes. The amount of this temporary upward adjustment will decline to zero on a straight-line basis over the three-month temporary adjustment period. However, Wells Fargo is not obligated to buy the notes from investors at any time. See “Summary Risk Factors—The Notes Will Not Be Listed On Any Securities Exchange And You May Not Be Able To Sell Them Prior To Maturity.”
© 2022 Citigroup Global Markets Inc. All rights reserved. Citi and Citi and Arc Design are trademarks and service marks of Citigroup Inc. or its affiliates and are used and registered throughout the world.
PS-17
| Market Linked Notes— Upside Participation to a Cap and Principal Return at Maturity Notes Linked to the Energy Select Sector SPDR® Fund due December 5, 2025 | |
| Appendix |
The material included in this Appendix was prepared by Wells Fargo and will be distributed to investors in connection with the offering of the notes described in this pricing supplement. The terminology used in the material included in this Appendix may differ from the terms used in this pricing supplement. The material included in this Appendix does not constitute terms of the notes. It is a general description of securities that share some features similar to the notes offered by this pricing supplement, but it does not relate specifically to the notes offered by this pricing supplement, and you should rely only on this pricing supplement (excluding the Appendix) and the accompanying product supplement, prospectus supplement and prospectus for a description of the specific terms of the notes offered by this pricing supplement.
PS-18

Market Linked Notes
Upside Participation to a Cap and Principal Return at Maturity

This material was prepared by Wells Fargo Securities, LLC, a registered broker- dealer and separate non-bank affiliate of Wells Fargo & Company. This material is not a product of Wells Fargo & Company research departments. Please see the relevant offering materials for complete product descriptions, including related risk and tax disclosure. |
MARKET LINKED NOTES WITH UPSIDE PARTICIPATION TO A CAP AND PRINCIPAL RETURN AT MATURITY ARE NOT DEPOSITS OR OTHER OBLIGATIONS OF A DEPOSITORY INSTITUTION AND ARE NOT INSURED BY THE FEDERAL DEPOSIT INSURANCE CORPORATION, THE DEPOSIT INSURANCE FUND OR ANY OTHER GOVERNMENTAL AGENCY OF THE UNITED STATES OR ANY OTHER JURISDICTION.
Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity have complex features and are not appropriate for all investors. Before deciding to make an investment, you should read and understand the applicable preliminary pricing supplement and other related offering documents provided by the applicable issuer.
Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity |
Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity (“these Market Linked Notes”) offer a return linked to the performance of a market measure, such as an index, exchange-traded fund or a basket of indices or exchange-traded funds (the “underlying”). In contrast to a direct investment in the underlying, these Market Linked Notes provide for the repayment of principal at maturity even if the underlying declines (subject to the credit risk of the issuer), as well as the potential for a positive return at maturity based on the point to point
performance of the underlying during the term of these Market Linked Notes, subject to a specified maximum return.
These Market Linked Notes are designed for investors who seek exposure to any positive performance of an underlying, but without the downside market risk of a direct investment in the underlying. In exchange for this protection against downside market risk, you must be willing to forgo interest payments, dividends (in the case of equity underlyings) and participation in any appreciation of the underlying beyond the maximum return. The potential for a positive return and the repayment of principal apply at maturity only and, if the issuer defaults on its payment obligations, you could lose your entire investment.
These Market Linked Notes are unsecured debt obligations of the issuer. You will have no ability to pursue the underlying or any assets included in the underlying for payment.
A-2 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
The charts in this section do not reflect forgone dividend payments.
|
Direct investment payoff
For traditional assets, such as stocks, there is a direct relationship between the change in the level of the asset and the return on
the investment. For example, as the graph indicates, suppose you bought shares of a common stock at $100 per share. If you sold the shares at $120 each, the return on the investment (excluding any dividend payments) would be $20 per share, or 20%.
Similarly, if you sold the shares after the price decreased to $80 (i.e., a decline of 20%), this would result in a 20% investment loss (excluding dividends). |

Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
These Market Linked Notes, if held until maturity, offer the repayment of principal and the potential to receive a positive return at maturity that is based on the performance of an underlying as measured from a specified starting level to the closing level of the underlying on a calculation day shortly before maturity (the ending level). While these Market Linked Notes limit against losses, they also limit upside return potential due to the specified maximum return, as explained below.
To understand how these Market Linked Notes would perform under varying market conditions, consider a hypothetical Market Linked Note with the following terms:
| • | Principal return: 100%. These Market Linked Notes, if held until maturity, provide for the repayment of principal regardless of the performance of the underlying, subject to the ability of the issuer to make payments when due. If the issuer defaults on its payment obligations, you could lose your entire investment. |
| • | Participation rate: 100%. A participation rate determines how much of the appreciation of the underlying (if any) will be reflected in the payment at maturity on these Market Linked Notes, subject to the maximum return described below. A participation rate of 100% means that if the underlying appreciates from its starting level to its ending level, you will receive a return at maturity equal to 100% of that appreciation, subject to the maximum return described below. For example, if the underlying appreciates by 10%, you would receive a return at maturity equal to 10% (which is 100% of 10%). For some issuances of these Market Linked Notes, the participation rate may be greater than 100%, in which case you will participate on a leveraged basis in any appreciation of the underlying from its starting level to its ending level, subject to the maximum return. For example, if the participation rate is 110% and the underlying appreciates by 10%, you would receive a return at maturity equal to 11% (which is 110% of 10%). |
| • | Maximum Return: 50%. A maximum return effectively sets a ceiling above which you will not participate in further appreciation of the underlying. A maximum return of 50% means that you will not receive a positive return of more than 50% of the original offering price of these Market Linked Notes at maturity, even if the underlying appreciates by more than 50%. This results in a maximum payment at maturity of 150% of the original offering price. Note that the maximum return effectively reduces the participation rate in scenarios where the participation rate multiplied by the appreciation of the underlying would exceed the maximum return. The maximum return on a Market Linked Note may be greater than or less than 50%. |
A-3 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
| This information, including the graph to the right, is hypothetical and is provided for informational purposes only. It is not intended to represent any specific return, yield, or investment, nor is it indicative of future results. The graph illustrates the payoff on the hypothetical Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity described above for a range of percentage changes from the starting level to the ending level. |  |
This hypothetical Market Linked Note could outperform the underlying if the ending level of the underlying has declined from the starting level. Note that, because the value of the underlying does not incorporate dividends paid on the underlying, the return on these Market Linked Notes does not compensate you for any dividends paid on the underlying. All payments on these Market Linked Notes are subject to the ability of the issuer to make such payments to you when they are due, and you will have no ability to pursue the underlying or any assets included in the underlying for payment. If the issuer defaults on its payment obligations, you could lose your entire investment.
A-4 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
Determining payment at maturity
The diagram below illustrates how the cash payment on the stated maturity date for this hypothetical Market Linked Note would be calculated. The diagram below assumes an original offering price of $1,000 per security.

A-5 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
Estimated value of Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
The original offering price of these Market Linked Notes will include certain costs that are borne by you. Because of these costs, the estimated value of these Market Linked Notes on the pricing date will be less than the original offering price. If specified in the applicable pricing supplement, these costs may include the underwriting discount or commission, the hedging profits of the issuer’s hedging counterparty (which may be an affiliate of the issuer), and hedging and other costs associated with the offering and costs relating to the issuer’s funding considerations for debt of this type. See “General risks and investment considerations” herein and the applicable pricing supplement for more information.
The issuer will disclose the estimated value of these Market Linked Notes in the applicable pricing supplement. The estimated value of these Market Linked Notes will be determined by estimating the value of the combination of hypothetical financial instruments that would replicate the payout on these Market Linked Notes, which combination consists of a non-interest bearing, fixed-income bond and one or more derivative instruments underlying the economic terms of these Market Linked Notes. You should read the applicable pricing supplement for more information about the estimated value of these Market Linked Notes and how it is determined.
A-6 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
| Which investments are right for you? |
It is important to read and understand the applicable preliminary pricing supplement and other related offering documents and consider several factors before making an investment decision.
An investment in these Market Linked Notes may help you modify your portfolio’s risk-return profile to more closely reflect your market views. However, you will forgo interest payments, dividend payments (in the case of equity underlyings), and any return in excess of the applicable maximum return.
These Market Linked Notes are not appropriate for all investors, but may be appropriate for investors aiming to:
| • | Fully protect against market losses at maturity |
| • | Gain or increase exposure to different asset classes |
| • | Obtain exposure to an underlying with a different risk/return profile than a direct investment in that underlying |
| • | Seek the potential to outperform the underlying in a declining market or, if the participation rate is sufficiently greater than 100%, the potential to outperform the underlying in a low to moderately appreciating market |
You can find a discussion of risks and investment considerations on the next page and in the preliminary pricing supplement and other related offering documents for these Market Linked Notes. The following questions, which you should review with your financial advisor, are intended to initiate a conversation about whether these Market Linked Notes are right for you.
| • | What is your time horizon? Do you foresee liquidity needs? Will you be able to hold these investments until maturity? |
| • | Does full protection against market declines take precedence for you over uncapped returns, dividend payments, or fixed returns? |
| • | What is your outlook on the market? How confident are you in your portfolio’s ability to weather a market decline? |
| • | What is your sensitivity to the tax treatment for your investments? |
| • | Are you dependent on your investments for current income? |
| • | Are you willing to accept the credit risk of the applicable issuer in order to obtain the exposure to the underlying that these Market Linked Notes provide? |
Before making an investment decision, please work with your financial advisor to determine which investment products may be appropriate given your financial situation, investment goals, and risk profile.
A-7 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
| General risks and investment considerations |
These Market Linked Notes have complex features and are not appropriate for all investors. They involve a variety of risks and may be linked to a variety of different underlyings. Each of these Market Linked Notes and each underlying will have its own unique set of risks and investment considerations. Before you invest in these Market Linked Notes, you should thoroughly review the relevant preliminary pricing supplement and other related offering documents for a comprehensive discussion of the risks associated with the investment. The following are general risks and investment considerations applicable to these Market Linked Notes:
| • | Performance risk and opportunity costs. Because these Market Linked Notes do not offer a minimum return, the yield that you will receive on these Market Linked Notes may be less than the return you could earn on other investments, including a traditional interest-bearing debt security with the same maturity date of the applicable issuer or another issuer with a similar credit rating, and could be zero. |
| • | Limited upside. These Market Linked Notes are subject to a maximum return, which will limit your return potential. Because of the maximum return, the return you receive at maturity on these Market Linked Notes, if any, may be lower than the return you could have realized on a direct investment in the underlying held for the term of these Market Linked Notes. Furthermore, the effect of the participation rate will be progressively reduced for all ending levels exceeding the ending level at which the maximum return is reached. |
| • | Liquidity risk. These Market Linked Notes are not appropriate for investors who may have liquidity needs prior to maturity. These Market Linked Notes are not listed on any securities exchange and are generally illiquid instruments. Neither Wells Fargo Securities nor any other person is required to maintain a secondary market for these Market Linked Notes. Accordingly, you may be unable to sell your Market Linked Notes prior to their maturity date. If you choose to sell these Market Linked Notes prior to maturity, assuming a buyer is available, you may receive less in sale proceeds than the original offering price. |
| • | Market value uncertain. These Market Linked Notes are not appropriate for investors who need their investments to maintain a stable value during their term. The value of your Market Linked Notes prior to maturity will be affected by numerous factors, such as performance, volatility, and dividend rate, if applicable, of the underlying; interest rates; the time remaining to maturity; the correlation among basket components, if applicable; and the applicable issuer’s creditworthiness. Wells Fargo Securities anticipates that the value of these Market Linked Notes will always be at a discount to the original offering price plus the maximum return. |
| • | Costs to investors. The original offering price of these Market Linked Notes will include certain costs that are borne by you. These costs will adversely affect the economic terms of these Market Linked Notes and will cause their estimated value on the pricing date to be less than the original offering price. If specified in the applicable pricing supplement, these costs may include the underwriting discount or commission, the hedging profits of the issuer’s hedging counterparty (which may be an affiliate of the issuer), hedging and other costs associated with the offering, and costs relating to the issuer’s funding considerations for debt of this type. These costs will adversely affect any secondary market price for these Market Linked Notes, which may be further reduced by a bid-offer spread. As a result, unless market conditions and other relevant factors change significantly in your favor following the pricing date, any secondary market price for these Market Linked Notes is likely to be less than the original offering price. |
| • | Credit risk. Any investment in these Market Linked Notes is subject to the ability of the applicable issuer to make payments to you when they are due, and you will have no ability to pursue the underlying or any assets included in the underlying for payment. If the issuer defaults on its payment obligations, you could lose your entire investment. In addition, the actual or perceived creditworthiness of the issuer may affect the value of these Market Linked Notes prior to maturity. |
| • | No periodic interest or dividend payments. These Market Linked Notes do not typically provide periodic interest. These Market Linked Notes linked to equity underlyings do not provide for a pass through of any dividend paid on the equity underlyings. |
| • | Estimated value considerations. The estimated value of these Market Linked Notes that is disclosed in the applicable pricing supplement will be determined by the issuer or an underwriter of the offering, which underwriter may be an affiliate of the issuer and may be Wells Fargo Securities. The estimated value will be based on the issuer’s or the underwriter’s proprietary pricing models and assumptions and certain inputs that may be determined by the issuer or underwriter in its discretion. Because other dealers may have different views on these inputs, the estimated value that is disclosed in the applicable pricing supplement may be higher, and perhaps materially higher, than the estimated value that would be determined by other dealers in the market. Moreover, you should understand that the estimated value that is disclosed in the applicable pricing supplement will not be an indication of the price, if any, at which Wells Fargo Securities or any other person may be willing to buy these Market Linked Notes from you at any time after issuance. |
A-8 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
| • | Conflicts of interest. Potential conflicts of interest may exist between you and the applicable issuer and/or Wells Fargo Securities. For example, the applicable issuer, Wells Fargo Securities, or one of their respective affiliates may engage in business with companies whose securities are included in the underlying, or may publish research on such companies or the underlying. In addition, the applicable issuer, Wells Fargo Securities, or one of their respective affiliates may be the calculation agent for the purposes of making important determinations that affect the payments on these Market Linked Notes. Finally, the estimated value of these Market Linked Notes may be determined by the issuer or an underwriter of the offering, which underwriter may be an affiliate of the issuer and may be Wells Fargo Securities. |
| • | Effects of trading and other transactions. Trading and other transactions by the applicable issuer, Wells Fargo Securities, or one of their respective affiliates could affect the underlying or the value of these Market Linked Notes. |
| • | Basket risk. If the underlying is a basket, the basket components may offset each other. Any appreciation of one or more basket components may be moderated, wholly offset, or more than offset, by depreciation of one or more other basket components. |
| • | ETF risk. If the underlying is an exchange-traded fund (ETF), it may underperform the index it is designed to track as a result of costs and fees of the ETF and differences between the constituents of the index and the actual assets held by the ETF. In addition, an investment in these Market Linked Notes linked to an ETF involves risks related to the index underlying the ETF, as discussed in the next risk consideration. |
| • | Index risk. If the underlying is an index, or an ETF that tracks an index, your return on these Market Linked Notes may be adversely affected by changes that the index publisher may make to the manner in which the index is constituted or calculated. Furthermore, if the index represents foreign securities markets, you should understand that foreign securities markets tend to be less liquid and more volatile than U.S. markets and that there is generally less information available about foreign companies than about companies that file reports with the U.S. Securities and Exchange Commission. Moreover, if the index represents emerging foreign securities markets, these Market Linked Notes will be subject to the heightened political and economic risks associated with emerging markets. If the index includes foreign securities and the level of the index is based on the U.S. dollar value of those foreign securities, these Market Linked Notes will be subject to currency exchange rate risk in addition to the other risks described above, as the level of the index will be adversely affected if the currencies in which the foreign securities trade depreciate against the U.S. dollar. |
| • | Commodity risk. These Market Linked Notes linked to commodities will be subject to a number of significant risks associated with commodities. Commodity prices tend to be volatile and may fluctuate in ways that are unpredictable and adverse to you. Commodity markets are frequently subject to disruptions, distortions, and changes due to various factors, including the lack of liquidity in the markets, the participation of speculators, and government regulation and intervention. Moreover, commodity indices may be adversely affected by a phenomenon known as “negative roll yield,” which occurs when future prices of the commodity futures contracts underlying the index are higher than current prices. Negative roll yield can have a significant negative effect on the performance of a commodity index. Furthermore, for commodities that are traded in U.S. dollars but for which market prices are driven by global demand, any strengthening of the U.S. dollar against relevant other currencies may adversely affect the demand for, and therefore the price of, those commodities. |
| • | Currency risk. These Market Linked Notes linked to currencies will be subject to a number of significant risks associated with currencies. Currency exchange rates are frequently subject to intervention by governments, which can be difficult to predict and can have a significant impact on exchange rates. Moreover, currency exchange rates are driven by complex factors relating to the economies of the relevant countries that can be difficult to understand and predict. Currencies issued by emerging market governments may be particularly volatile and will be subject to heightened risks. |
| • | Bond risk. These Market Linked Notes linked to bond indices or exchange-traded funds that are comprised of specific types of bonds with different maturities and qualities will be subject to a number of significant risks associated with bonds. In general, if market interest rates rise, the value of bonds will decline. In addition, if the market perception of the creditworthiness of the relevant bond issuers falls, the value of bonds will generally decline. |
| • | Tax considerations. You should review carefully the relevant preliminary pricing supplement and other related offering documents and consult your tax advisors regarding the application of the U.S. federal tax laws to your particular circumstances, as well as any tax consequences arising under the laws of any state, local, or non-U.S. jurisdiction. |
A-9 | Market Linked Notes with Upside Participation to a Cap and Principal Return at Maturity
Always read the preliminary pricing supplement and other related offering documents.
These Market Linked Notes are offered with the attached preliminary pricing supplement and other related offering documents. Investors should read and consider these documents carefully before investing. Prior to investing, always consult your financial advisor to understand the investment structure in detail.
For more information about these Market Linked Notes and the structures currently available for investment, contact your financial advisor, who can advise you of whether or not a particular offering may meet your individual needs and investment requirements.
Wells Fargo Securities is the trade name for the capital markets and investment banking services of Wells Fargo & Company and its subsidiaries, including Wells Fargo Securities, LLC, a member of FINRA, NYSE, and SIPC, and Wells Fargo Bank, N.A.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC, members SIPC, separate registered broker-dealers and non-bank affiliates of Wells Fargo & Company.
© 2019 Wells Fargo Securities, LLC. All rights reserved. IHA-6368213
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- U.S. large-cap bank stocks: Q3 earnings preview
- Pasqal names Roger L. Chuchen as head of investor relations
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
CitiSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
